Digital Banking Neobank
App Development

Stateside Digitals builds custom digital banking and neobank apps for fintech founders and financial platforms across all 50 states, covering BaaS integration, account management, KYC and AML compliance, and real-time payment infrastructure.

Why The Digital Banking Market Needs The Right App

Traditional banks have given the digital banking market its opportunity by making the everyday banking experience as friction-filled as possible. A neobank wins not by offering more financial products but by making the products it does offer feel effortless: an account opened in minutes rather than days, a debit card that arrives before the weekend, and a balance that updates the moment a transaction settles rather than the next morning.

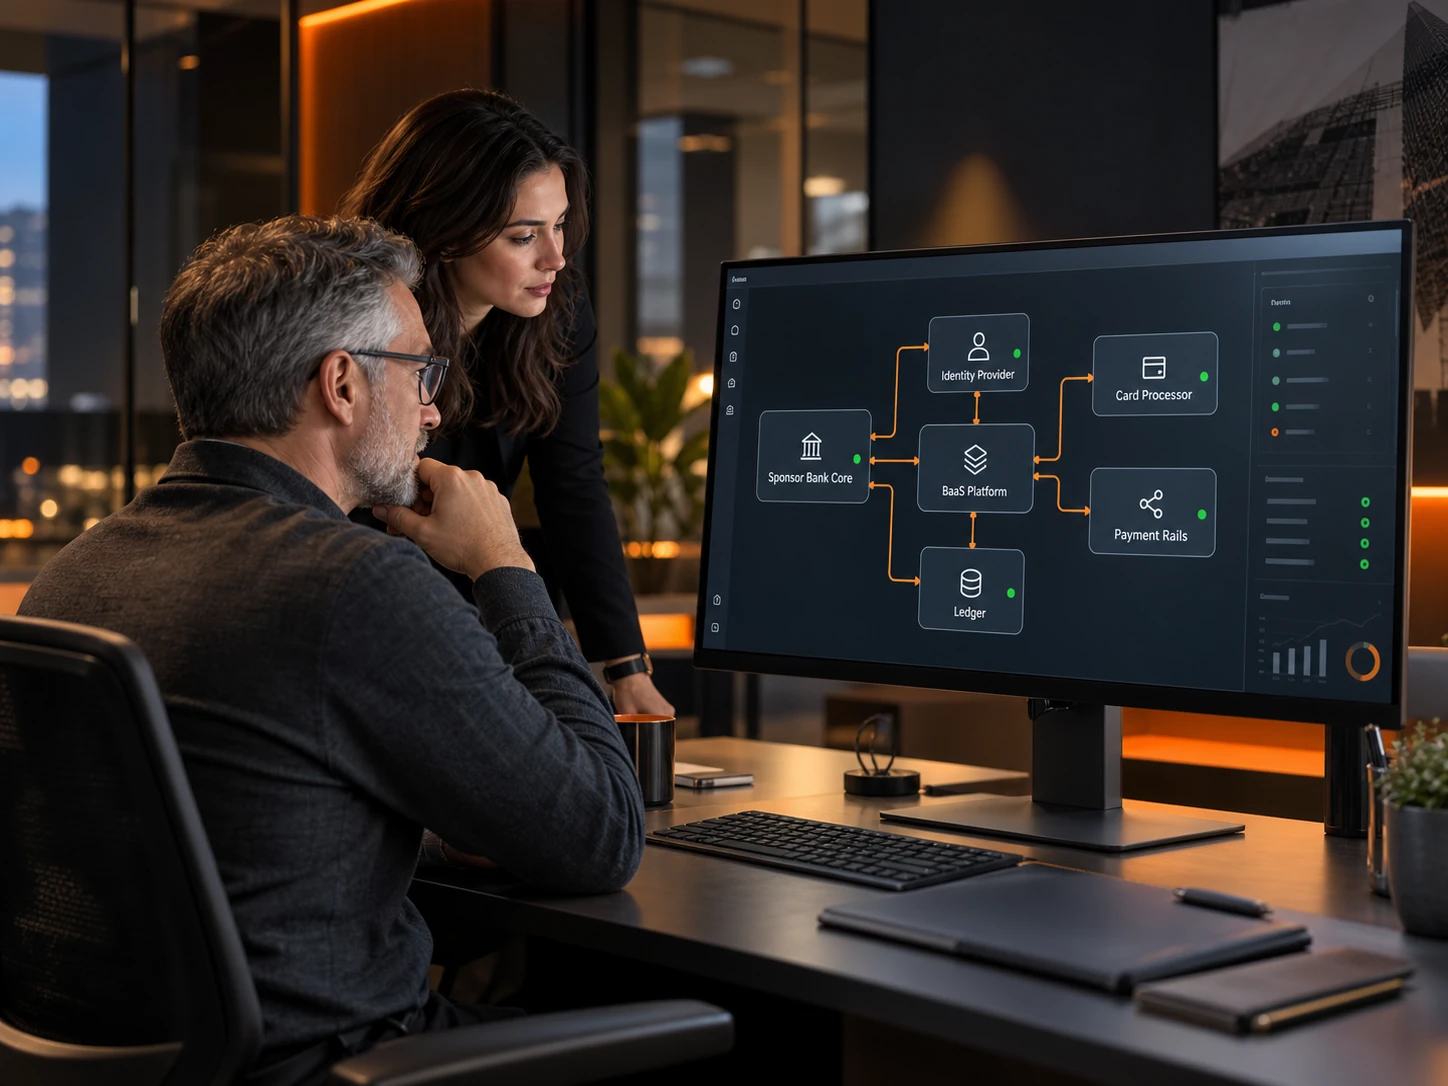
The infrastructure challenge is what most neobank founders underestimate. An account that holds money is not a database field — it is a regulated liability sitting on a bank’s balance sheet, connected to a payment network that settles transactions in real time, covered by FDIC insurance, and subject to BSA and AML obligations that apply from the first dollar deposited. Building the app is the easy part. Building the infrastructure underneath it correctly is what determines whether the neobank actually operates.

Our Digital Banking
App Development Services

01

Account and Card Management

Account opening, balance and transaction view, debit card management, spending controls, and the real-time notifications that make a banking app feel alive rather than lagging a day behind.
03

Payments and Money Movement

ACH transfers, wire payments, P2P money movement, bill pay, and external account linking through Plaid, with transaction status that updates in real time rather than the following business day.

Digital Banking App
Models We Build

Three platform models cover most of the neobank opportunity. The regulatory obligations, the BaaS requirements, and the feature priorities differ meaningfully between them.
01

Consumer Neobank App

A personal banking platform with FDIC-insured accounts, a debit card, spending categorisation, and the budgeting and savings tools that make a challenger bank worth switching to from an incumbent.

02

Business Banking Platform

A banking product for small and medium businesses, with multi-user accounts, role-based permissions, ACH and wire initiation, expense management, and accounting software integration.

03

Vertical or Community Neobank

A banking product built for a specific demographic, profession, or community, with account features and financial tools tailored to the financial patterns and needs of that group.

The Kind Of Experience
Account Holders Already Expect

A customer who uses Chime or Cash App as their primary account arrives at a new neobank with a baseline that traditional banks have been unable to set. Account opening that takes less than five minutes. Instant transaction notifications the moment a card is used. A balance that is accurate right now rather than reflecting yesterday’s settlement. Direct deposit that posts two days early. Missing any of those is not a minor product gap — it is the reason they have not switched from where they already bank.

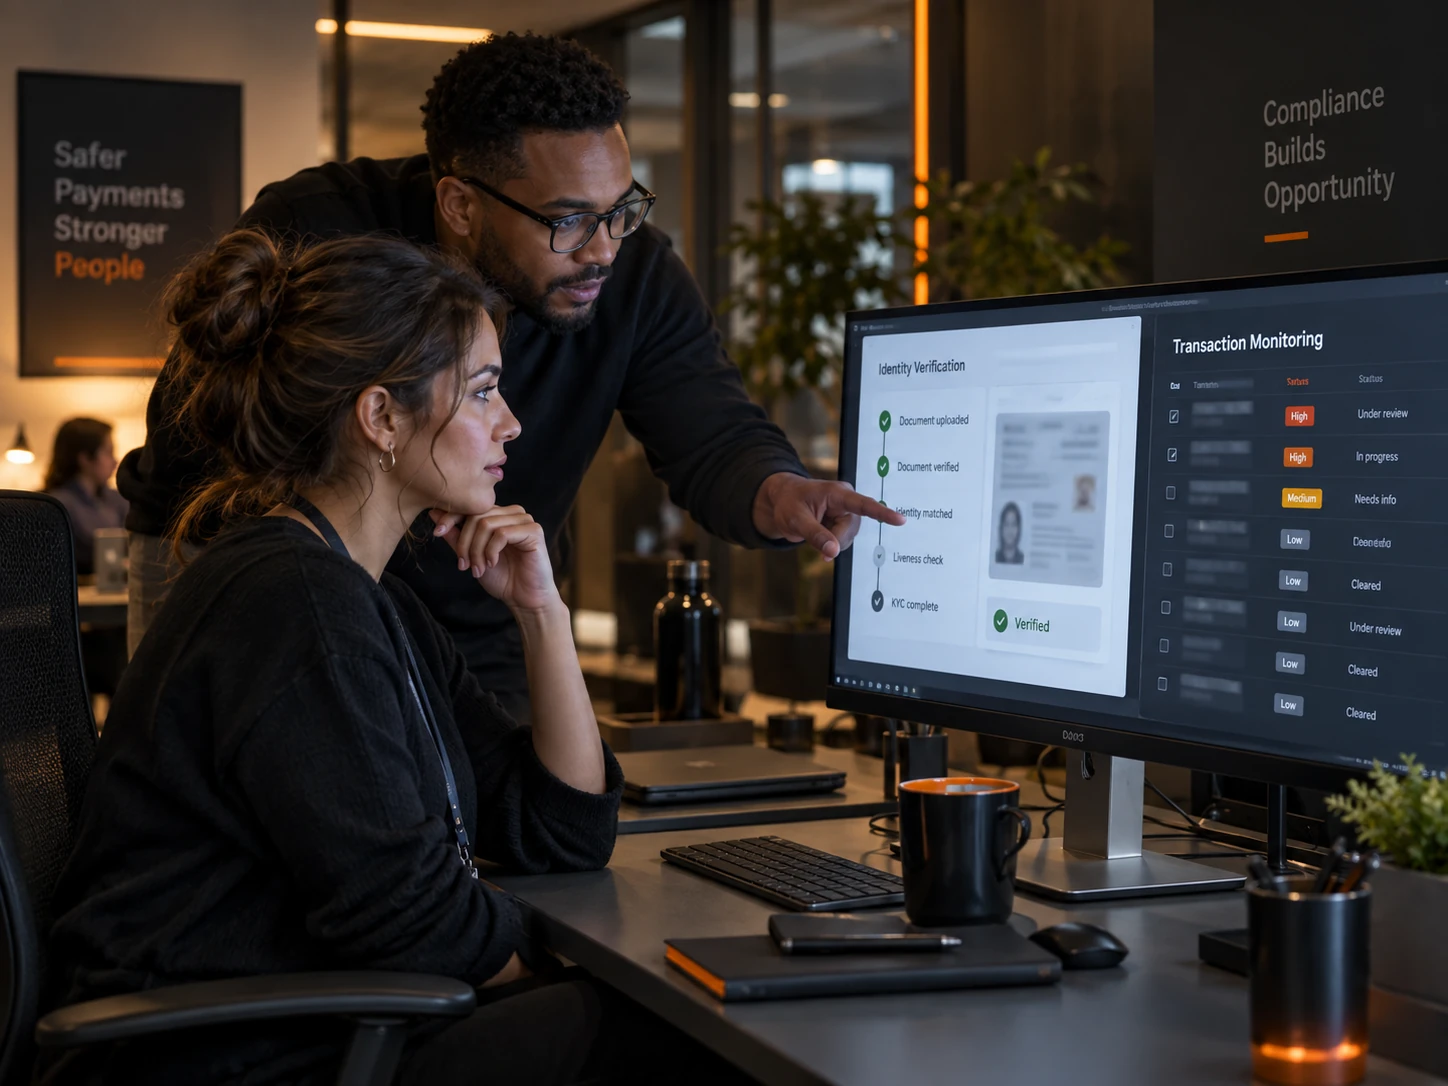
The compliance layer is what most neobank founders treat as a post-launch problem and almost always regret. KYC identity verification at account opening is required before a customer can deposit a dollar. Transaction monitoring for AML is a BSA obligation that applies to every account from day one. The SAR filing process has to exist and work correctly before regulators look for it. We design the compliance architecture before the first account feature is built, not after the first examiner’s question.

Key Features We Build, By User

05 features
  • Digital account opening with KYC verification
  • Real-time balance and transaction feed
  • Debit card controls and instant freeze
  • ACH transfers and external account linking
  • Spending insights and savings tools

How Much Does A
Digital Banking App Cost?

Cost depends mainly on which BaaS provider you integrate, how many account types you support, and how complex your compliance requirements are. As a general guide:
01

Consumer Neobank MVP

Core account, debit card, and payment features on a single BaaS provider with KYC and basic AML. These typically fall in the high five-figure range and take sixteen to twenty-four weeks.

02

Full Consumer Platform

Complete neobank with savings, P2P transfers, budgeting, external account linking, and advanced compliance tooling. These approach or exceed the six-figure range with a twenty to twenty-eight week build.

03

Business Banking Product

Business accounts with multi-user permissions, wire capabilities, expense management, and accounting integration. These sit in the six-figure range and are scoped individually due to integration complexity.

These are market ranges, not fixed quotes. We give you an itemized number after a short discovery call.

How We Work

01Discovery

We map your target customer, your BaaS provider options, your compliance obligations, and your monetisation model before any design decisions are made.

02Design

We prototype the account opening flow and the core banking experience before development starts, testing the KYC handoff and the transaction notification timing specifically.

03Development

We build in sprints with regular check-ins, with BaaS integration and compliance tooling built alongside the customer-facing app rather than after it.

04Testing

Every build is tested against the BaaS sandbox with real transaction scenarios before release so payment flows and compliance logic are validated before real money moves.

05Launch and Support

We handle App Store and Google Play submission and stay on for BaaS updates, regulatory changes, and new product or account type additions after launch.

Technologies We Use
For Digital Banking
App Development

We build neobank apps in React Native for iOS and Android. The backend runs on Node.js with PostgreSQL for ledger and account data, with Redis for real-time transaction state. BaaS integration connects to Unit, Column, Synctera, or Treasury Prime depending on your product requirements and partner bank relationships. External account linking uses Plaid. Payments and card management go through the BaaS provider’s APIs. All infrastructure runs in a SOC 2-compliant cloud environment.
  • React Native
  • TypeScript
  • JavaScript
  • Node.js
  • PostgreSQL
  • Redis
  • Plaid
  • Unit
  • GraphQL
  • AWS
  • SOC 2
  • Card Issuance

Why Choose Stateside Digitals For
Digital Banking App Development

Frequently Asked Questions

Do we need a banking licence to launch a neobank?

In most cases, no. Banking-as-a-Service providers including Unit, Column, Synctera, and Treasury Prime allow you to offer FDIC-insured accounts and debit cards through a partner bank without holding your own charter. You still have BSA compliance obligations from day one, and legal counsel is essential before selecting a BaaS partner.

What does KYC and AML compliance actually involve?

Which BaaS provider should we use?

Can you integrate with Plaid for account linking?

How is this different from your Banking industry page?

Let’s Build Your
Neobank App

Tell us who your account holders are, which BaaS provider you are considering, and what your compliance counsel has advised, and we will scope a neobank built around all three.

FILL THE FORM

Stateside Digitals
@2026
LET’s CONNECT